Europe's banks asked Brussels for a shortcut on Monday and were told no. Maria Luís Albuquerque, the Commissioner in charge of financial services, rejected a request from the heads of eleven of the continent's largest lenders to split the Commission's July banking package in two, so that capital-rule reforms could move ahead while the long-stalled European deposit insurance scheme waits. Her answer was that there is no low-hanging fruit to pick, that everything in the package is connected, and that the real reason European banks trail their American rivals is scale rather than onerous capital requirements.
The Commission unveiled its banking competitiveness proposal in July as a single package. Last week, eleven bank chiefs, including those of Santander, BNP Paribas and UBS, wrote to Brussels urging faster action on capital rules and an immediate moratorium on any capital increases while the proposals are debated, rather than waiting for agreement on a deposit guarantee scheme that has been stuck since 2015. Albuquerque's response, given in a television interview, was that a meaningful reform has to be treated as a package. She was equally direct about what she thinks is wrong with European banking: not the rulebook, but the absence of institutions big enough to compete across borders. Cross-border deals between lenders in different member states, she said, should have happened a long time ago, and the Commission's job is to make sure the regulatory framework does not stand in the way of good business cases for scale.
She also conceded ground elsewhere. A separate plan to streamline supervision of Europe's capital markets is likely to be diluted after members of the European Parliament pushed for sweeping changes.
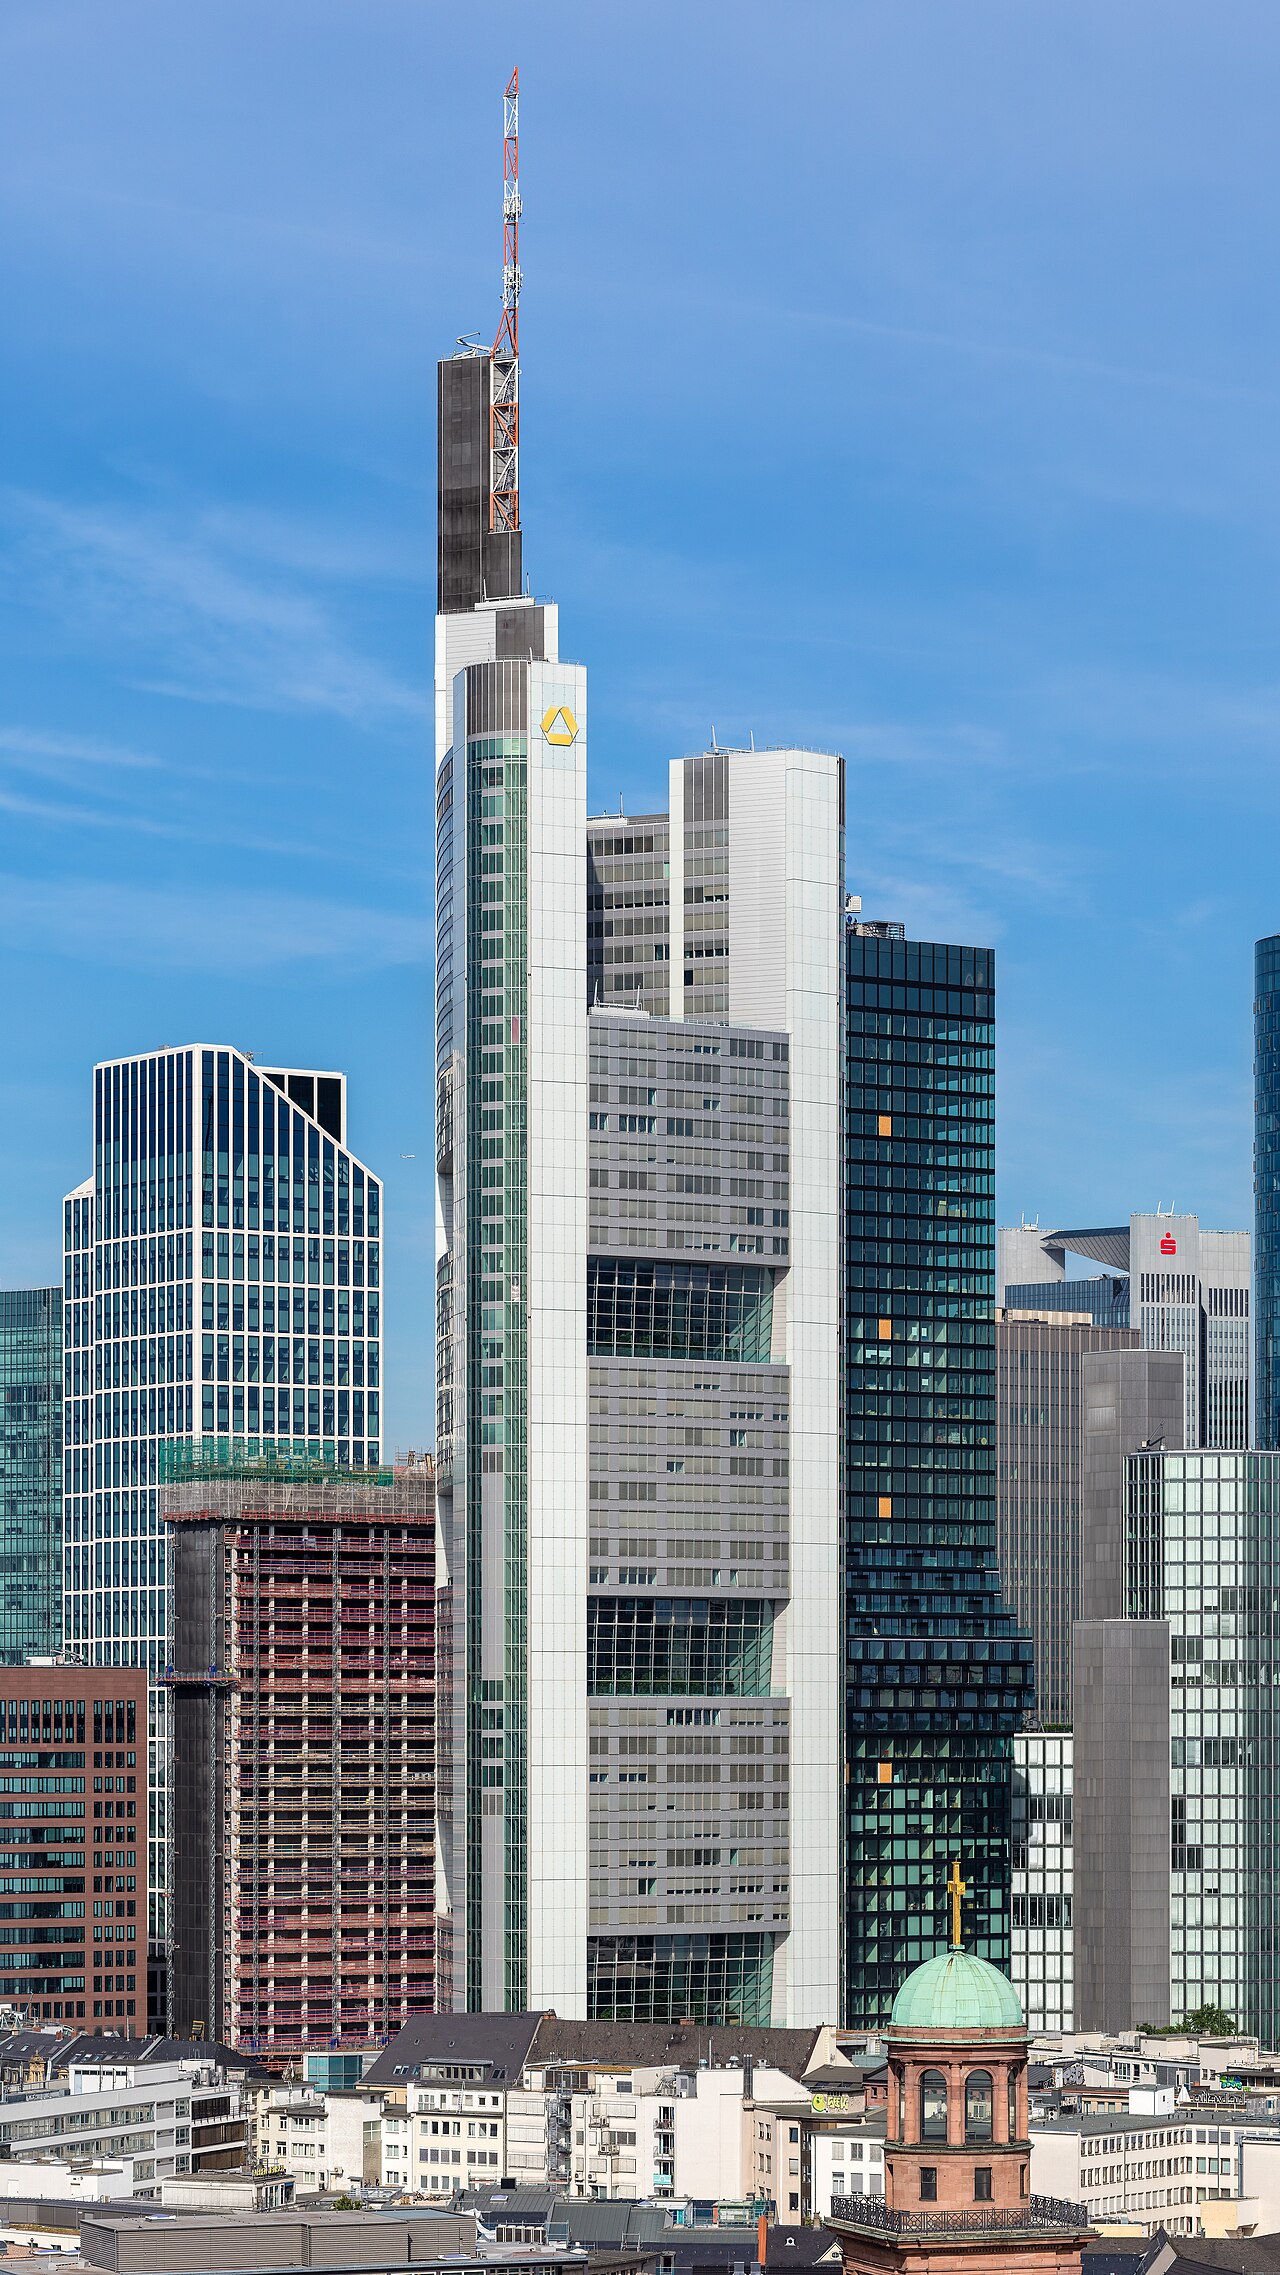
The Commissioner's remarks landed on the day the test case for European bank consolidation moved from confrontation to bargaining. German Finance Minister Lars Klingbeil received UniCredit chief executive Andrea Orcel in Berlin and set out his conditions for a takeover of Commerzbank: the bank stays listed, keeps its headquarters in Frankfurt, and keeps financing German medium-sized companies at home and abroad. The government, which still holds 13.3 per cent of Commerzbank from the financial-crisis bailout, has spent two years trying to block Orcel, who built a stake of close to 50 per cent after taking Berlin and the bank by surprise in 2024. It had rejected UniCredit's latest offer as too low. A finance ministry spokesperson said the matter is no longer about a hostile takeover but about finding the best path forward for both banks. Klingbeil said the further negotiations must be conducted responsibly; Orcel called it a good and constructive initial discussion that would be swiftly followed by others. A combined bank would hold more than €1.3 trillion in assets across the eurozone's two largest economies.
Germany is not the only place where the consolidation argument is live. Monte dei Paschi di Siena said on Monday it would keep pursuing its twin offers for Banco BPM and Banca Generali even if Intesa Sanpaolo buys it, a reminder that Italy's banking map is being redrawn from several directions at once.
The scale argument spread beyond banks. Euronext chief executive Stéphane Boujnah told the Financial Times that a merger of the exchange businesses of Euronext and Deutsche Börse would make sense and could create market infrastructure of planetary scale, while stressing no talks are taking place; Deutsche Börse said the same. Shares in both groups rose about 2 per cent on Monday regardless, and any such deal would face antitrust hurdles that have sunk previous attempts.
The least glamorous item of the day may matter most. On 14 September Europe's consolidated tape went live, displaying supply and demand data for shares and exchange-traded funds across the region's trading venues. The United States has had a national tape for about five decades. The EU has long identified piecemeal trading data, alongside diverging legal systems and patchy settlement infrastructure, as a reason investors treat Europe as many small markets rather than one.
Monday drew a line under a decade of Brussels telling banks it wants a banking union and then letting the deposit scheme sit in the drawer. Albuquerque's message is that the Commission will not let the industry pick the parts of the package it likes, and that the price of lighter rules is accepting bigger, cross-border banks. Berlin's shift from blocking UniCredit to setting conditions for it is the first sign a large member state accepts that trade. The risk is that scale arrives on political terms rather than economic ones: a Commerzbank that stays listed in Frankfurt with a protected lending mandate is a merger with strings, and other capitals will study the strings. The consolidated tape is the quieter but more durable change. It does not create a single European market by itself, but it removes one of the excuses for saying there isn't one.